The Chicago Journal

What to Do When an Algorithm May Have Rejected You: AI Bias in Hiring

You spent an hour tailoring your resume to the posting. The rejection landed ninety minutes later. That speed can point to an automated filter or a preset workflow, but it doesn’t tell you who or what made the final call. That is why AI bias in hiring is far easier to suspect than to establish.

You usually can’t tell from a rejection email alone whether an algorithm screened you. Sometimes the timing gives it away, or the wording reads like a template. Getting the same result across similar roles helps too. But documentation and one direct question to the employer are worth more than guessing. If you’re asking how to tell if an AI rejected your job application, the honest answer is that no single clue confirms it.

What AI Bias in Hiring Can Look Like

Automated Screening Is Broader Than Resume Scanning

AI hiring bias describes an automated hiring process that produces or reinforces systematically different outcomes for applicants based on a characteristic such as race, sex, age, or disability. A tool can skew outcomes without anyone designing it to discriminate.

Automation can enter the process through resume ranking, knockout questions, online assessments, interview analysis, candidate matching, or job ad delivery. And sometimes a fast decision has a mundane cause: a missing license or a work-authorization answer that closed the file the moment you hit submit.

Before you ever apply, AI decides which job ad reaches you. Once your resume arrives, a model may rank it too. It can determine whether an assessment hits your inbox and whether a person ever opens the file. Automation by itself doesn’t prove bias. It makes the decision path harder for you to see.

How AI Is Affecting Hiring Decisions

AI is affecting hiring by helping employers advertise roles, rank resumes, administer assessments, and decide which applicants receive human review. It can speed up high-volume screening, but it can also reproduce patterns in training data or apply flawed criteria at scale. How much this matters depends on the tool itself, the employer’s process, and how seriously people review what the software produces.

A Concrete Example of Biased Output

Researchers at the University of Washington ran an experiment in 2024. They handed large language models resumes that matched in every way except the names, which signaled different demographic groups. Wilson and Caliskan (2024) found that the systems favored white-associated names 85% of the time and male-associated names 52% of the time. Same qualifications. Different names.

That experiment describes model behavior. It says nothing about the company that turned you down. It doesn’t establish that your employer used a similar system or reached a discriminatory decision. What it does show is that measurable skew can persist inside a tool presented as neutral.

Preserve Evidence Before Pages and Messages Disappear

Capture the Job and Application Record

Postings come down. Portals purge closed applications. Recruiters move on. Work through this sequence in order because each step gets harder the longer you wait:

Wondering what evidence to keep after an automated hiring rejection? The core file is the posting, submitted application, timestamps, notices, and assessment records.

1. Save the complete job posting as a PDF or screenshot. Capture the qualifications, location, requisition number, salary information, posting date, and URL.

2. Save the resume, cover letter, application answers, and portfolio materials in the exact form you submitted them.

3. Record the submission and rejection times and time zone.

4. Preserve every email, text message, portal notice, chatbot exchange, assessment invitation, score report, and status change.

5. Write down any accommodation request, accessibility problem, recruiter response, and deadline while the details are fresh.

Don’t alter the original files. Build a separate chronology, one line per event, noting what happened and when. Together, these records show what criteria the employer announced and what information it received, and gaps tend to surface in the timeline. If you need to document hiring discrimination from algorithms, keep the chronology factual: record what happened, when it happened, and what the employer or vendor said.

Keep Assessment and Accessibility Details

A score alone rarely explains how an assessment worked. Write down the assessment name and the vendor behind it. Note how long it took to complete and which device you used. Record the instructions you received and any technical error that interrupted you, along with whether anyone offered a retake.

Record whether the tool required video or audio and whether timed responses or controls you couldn’t operate with a keyboard put you at a disadvantage. If you requested an accommodation, keep that request in its own folder, separate from general recruiter correspondence. Note who received it and what response came back.

Use Legal Background Carefully

Employers rarely volunteer how their screening works, so the record you build provides the basis for a fact-specific review. Sanford Heisler Sharp McKnight, a firm that litigates employment discrimination and algorithmic-bias claims, lays out in its AI bias in hiring guide how automated tools reach protected groups and how a timeline of postings, assessment reports, and messages can be tested against those protections. A fast timestamp, standing alone, still proves nothing about any single rejection.

Ask the Recruiter Questions They Can Actually Answer

Can I Ask a Recruiter If AI Screened My Resume?

You can ask if an automated tool screened or scored your application before it was rejected. A recruiter may not know the technical details or may decline to share them. A narrow written question still creates a clearer record than an accusation of bias. Keep it to one email:

● Was my application screened, ranked, scored, or rejected using an automated tool?

● Did a person review my application before the rejection was sent?

● Did a knockout question or minimum qualification determine the result?

● What assessment or screening vendor was used?

● Can I receive my assessment score, report, or an explanation of the criteria?

● Is there a process for correcting inaccurate information or requesting reconsideration?

● Who handles questions about disability accommodations in the application process?

Recognize Common Dead Ends

Generic rejection language reveals little about how the screening worked. The same is true of silence or a statement that another candidate was selected. A recruiter who can’t respond isn’t necessarily concealing anything. Many coordinators genuinely don’t know which vendor scores the assessments they send out.

Send one concise follow-up, not five. If a report contains inaccurate information, ask specifically about the correction process. Then save the employer’s word-for-word reply, including any statement that a human reviewed your file.

When Repeated Rejections Deserve Closer Review

Look for a Pattern, Not a Magic Number

No universal number of rejections proves discrimination. A pattern becomes more meaningful when comparable applications produce consistent outcomes under similar conditions, particularly when the timing repeats, or the same assessment platform appears at the same stage of the process. An accommodation problem that repeatedly goes unresolved may warrant closer attention, too.

Comparisons worth tracking include repeated applications to one employer and applications routed through the same screening vendor. An outcome that shifts after a material profile detail changes is worth noting, too. Don’t run deceptive tests or submit false information to see what happens.

What Large-Scale Research Can and Cannot Tell You

A 2026 Stanford University study analyzed four million job applications and found racial bias in algorithmic screening. Bommasani et al. (2026) reported that 25.87% of Black applicants and 14.74% of Asian applicants experienced algorithmic discrimination. The research reported an even starker figure for repeated attempts: 10% of candidates who submitted at least four applications were rejected by an algorithm for every job they applied to.

Population-level findings can’t establish what happened to your file. Still, repeated rejection may deserve closer review when similar applications keep reaching the same automated stage, or when unusually rapid timing and an unexplained score recur. The pattern is a reason to preserve records and seek a fact-specific review, not proof on its own.

Escalate Based on the Record

Closer review may make sense when an employer confirms automated scoring, a score report contains data you can show is wrong, or an accommodation request goes unanswered, and the same outcome repeats for roles you appear qualified to perform. Your options hinge on your jurisdiction and how the decision was made, which is why the record you built matters more than speculation.

Build a Record Before Drawing a Conclusion

A rejection that arrives in minutes gives you a reason to ask a question, but it rarely provides certainty. Your strongest next move is to preserve the original record and ask one narrow written question. Document any accommodation issue, and weigh repeated outcomes on comparable facts, not on a hunch.

Start by saving the rejection email in the same folder as the original posting and your submission timestamp. Label the folder with the requisition number.

Disclaimer: This article is provided for general informational and educational purposes only and should not be considered legal advice. Reading this article does not create an attorney-client relationship. Laws governing AI-assisted hiring and employment discrimination vary by jurisdiction and may change over time. Because every situation is unique, individuals who believe they have experienced bias during the hiring process should consult a qualified employment attorney regarding their specific circumstances.
Revenue-Based Financing: How It Works and Who It’s For

Revenue-based financing ties repayment directly to how a business actually performs, rather than locking in a fixed payment regardless of how a given month goes. For businesses with genuinely variable revenue, this structure can feel considerably more forgiving than a traditional fixed-payment loan.

What Makes Revenue-Based Financing Different

Unlike a term loan with a fixed monthly payment, revenue-based financing structures repayment as a percentage of ongoing revenue, meaning the actual dollar amount collected rises and falls alongside how the business is genuinely performing. A strong month produces a larger payment, moving repayment along faster, while a slower month produces a smaller one, easing the burden precisely when cash is tightest. This built-in flexibility is the defining feature that distinguishes this product from most other financing structures.

Who Tends to Benefit Most From This Structure

Fundivi, a direct lender and hybrid funding platform, offers revenue-based financing as one of nine core products, and it tends to suit businesses with genuinely seasonal or cyclical revenue particularly well. A business that earns considerably more during certain months than others often finds a fixed monthly payment mismatched to its actual cash flow pattern, paying the same amount during a lean month as during a strong one. Revenue-based financing removes this mismatch by design, scaling the payment to match the revenue that actually came in.

How Qualification Works for This Product

Because revenue-based financing repayment depends directly on ongoing revenue, qualification for this product tends to weigh actual cash flow and revenue consistency more heavily than extended credit history. A business owner curious whether their numbers realistically support this structure can check directly using Fundivi’s self-underwriting engine, which evaluates revenue, average daily balance, negative balance days, time in business, credit score, leverage, and open financing positions against published thresholds, with no credit pull and nothing submitted anywhere.

This evaluation matters specifically for revenue-based financing because a business with genuinely strong but variable revenue may look meaningfully different under this kind of holistic review than it would under a credit-score-dominant evaluation that doesn’t account for actual cash flow strength.

Comparing Revenue-Based Financing to a Fixed-Payment Alternative

A business owner deciding between revenue-based financing and a traditional fixed-payment product benefits from thinking honestly about their own revenue pattern. A business with steady, predictable monthly revenue may not gain much from the flexibility revenue-based financing offers, since a fixed payment would already align comfortably with a fairly consistent income stream. A business with genuinely unpredictable or seasonal revenue, by contrast, stands to benefit considerably more, since the built-in flexibility directly addresses the specific risk a fixed payment would otherwise create during a slower stretch.

Understanding the True Cost of a Revenue-Based Offer

Revenue-based financing, like many alternative financing products, is often priced using a factor rate rather than a traditional interest rate. This makes the true cost of a specific offer genuinely harder to interpret at a glance than it might first appear. Converting a factor rate into a real, annualized figure requires accounting for the total amount to be repaid, the expected timeline based on the business’s revenue pattern, and the actual payment frequency, exactly the calculation Fundivi’s cost calculator performs directly, revealing a true cost that often looks meaningfully different from the factor rate alone.

What to Consider Before Choosing This Product

A business owner considering revenue-based financing should think through how the percentage-of-revenue structure will feel during both strong and weak months, since a considerably larger payment during an unusually strong month is the direct trade-off for a smaller one during a weak month. This dynamic works well for businesses genuinely comfortable with variable payment amounts, but a business owner who strongly prefers the predictability of a fixed payment, even during a strong month, may find a traditional term loan a more comfortable fit despite revenue-based financing’s built-in flexibility.

How Revenue-Based Financing Compares Across a Business’s Growth Trajectory

A business’s relationship with revenue-based financing often evolves as the business itself matures. A newer or rapidly growing business, still working out exactly how predictable its month-to-month revenue will become, often benefits considerably from this structure’s built-in adaptability, since a fixed payment sized around an early, potentially unreliable revenue estimate carries genuine risk if that estimate turns out to be optimistic. As a business’s revenue pattern becomes more established and predictable over time, the relative advantage of a variable payment structure may diminish somewhat, since a fixed payment becomes easier to size accurately against a track record the business has now demonstrated consistently.

This doesn’t mean revenue-based financing becomes unsuitable for an established business; many mature businesses continue to value the built-in cushion during genuinely unpredictable stretches, whether from a supply chain disruption, a shift in customer demand, or a broader economic slowdown. Rather, it suggests that a business owner’s comfort level with this structure should be reassessed periodically, alongside how genuinely established and predictable the business’s revenue pattern has become.

Why Industry Context Shapes How Well This Product Fits

Certain industries naturally lend themselves to revenue-based financing more than others, simply based on how revenue typically flows. Businesses with pronounced seasonal cycles, retail around major holidays, landscaping through warmer months, tax preparation concentrated in early spring, tend to find the percentage-of-revenue structure particularly well matched to their underlying cash flow pattern. Businesses with more consistently distributed revenue throughout the year may find less practical difference between this structure and a traditional fixed payment, since their revenue rarely swings dramatically enough for the flexibility to matter as much in practice.

Business owners uncertain whether their own industry pattern genuinely favors this structure benefit from reviewing several months of actual revenue history before deciding, since a general industry tendency doesn’t always predict how a specific individual business actually performs. A business owner who reviews their own numbers honestly, rather than relying on a broad industry assumption, arrives at a considerably more accurate sense of whether revenue-based financing’s built-in flexibility genuinely matches their own situation.

Frequently Asked Questions

Does Revenue Based Financing Require Strong Personal Credit?

Credit score factors into the overall evaluation, but revenue and cash flow strength typically carry meaningful weight alongside it, making this product accessible to businesses with a range of credit profiles.

How Is The Specific Repayment Percentage Determined?

The percentage is set based on a full underwriting review considering the business’s specific revenue pattern and overall financial profile, not a single fixed rate applied uniformly to every business.

Can I Pay Off A Revenue-Based Financing Arrangement Early?

Specific early repayment terms vary by offer and are worth confirming directly as part of reviewing any specific agreement before signing.

Is This Product Only For Seasonal Businesses?

No. While seasonal businesses often benefit considerably, any business with genuinely variable revenue can find this structure a comfortable fit.

How Do I Know If This Product Fits My Business Better Than A Term Loan?

Working through Fundivi’s funding product matcher provides a direct, reasoned recommendation based on your specific revenue pattern and funding need.

Getting Started

Business owners curious whether revenue-based financing fits their situation can check their qualification outlook, confirm product fit through the matcher, and once an offer arrives, use the cost calculator to understand its true annualized cost before deciding.

Disclaimer: This article is for general informational and educational purposes only and does not constitute financial, legal, or lending advice. Financing products, eligibility requirements, repayment terms, and costs vary by provider and applicant. Business owners should carefully review all terms and consult a qualified financial or legal professional before entering into any financing agreement.

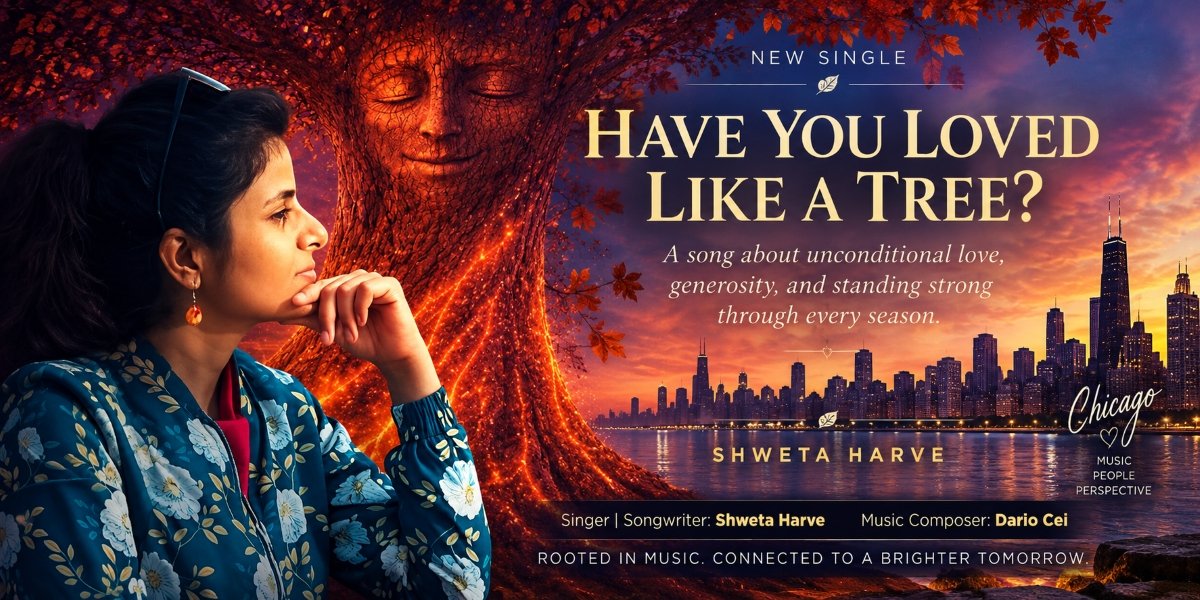
Deep Roots in the Windy City, Shweta Harve’s “Have You Loved Like a Tree?” Finds Meaning in Chicago

By: Claire Donovan

Chicago knows something about standing through difficult seasons.

This is a city where summer arrives like a celebration, and winter tests everybody’s commitment. Trees that spend July forming green canopies over neighborhood streets can appear skeletal by January, battered by lakefront winds and buried beneath snow. Then spring comes, and somehow they begin again.

That cycle makes Shweta Harve’s “Have You Loved Like a Tree?” feel particularly meaningful when heard from a Chicago perspective. The Dallas-based singer-songwriter builds the single around a deceptively simple question: What would it mean to love another person the way a tree exists in the world?

Harve isn’t really singing about trees, of course.

She’s singing about endurance.

About giving.

About remaining present when the season changes.

Those ideas fit Chicago remarkably well.

Chicago has always been a city of neighborhoods, where identity can change within a few train stops but community remains essential. From Bronzeville and Pilsen to Hyde Park, Uptown and Rogers Park, generations of people have created lives through relationships that endure because somebody decided to remain standing when things became difficult.

Harve turns that kind of steadfastness into the emotional center of her song.

The tree becomes an uncomplicated but surprisingly effective symbol. It provides shade without demanding payment. Its branches offer shelter. Its roots keep it grounded. It gives something to the world simply by being there.

The longer Harve develops the idea, the less sentimental it becomes.

Because loving like a tree sounds easy until you consider what she’s actually asking.

Can you give without calculating what you’ll receive?

Can you offer someone shelter during their worst season?

Can you stay rooted while everything around you changes?

Musically, “Have You Loved Like a Tree?” approaches those questions with restraint. The production leaves plenty of space around Harve’s vocal, favoring warmth and reflection instead of chasing the oversized sonic impact common to contemporary pop.

That makes sense for the material.

Chicago listeners come from a city with an extraordinary musical inheritance: blues, gospel, house, jazz, soul, rock and hip-hop have all flourished here. Those traditions may sound radically different, but the best examples share one quality: emotional truth matters more than decoration.

Harve understands that principle.

Her performance isn’t designed as a showcase for vocal acrobatics. Instead, she delivers the song with sincerity and control, allowing the words to remain the focal point. There is conviction in her voice without the feeling that she’s trying to convince you.

That difference matters.

The song becomes even more interesting alongside Harve’s earlier “What the Troll?”, which reached No. 26 on the Mediabase Adult Contemporary chart. That single confronted online trolling, cyberbullying, and the strange cruelty that can emerge when human interaction is filtered through anonymity and screens.

Put the two songs together, and they almost behave like a question and response.

“What the Troll?” examines disconnection.

“Have You Loved Like a Tree?” searches for connection.

One looks at what happens when people forget the humanity of strangers. The other asks whether generosity, patience, and unconditional support might help us remember it.

For an independent artist, that’s the beginning of a compelling creative identity. Harve isn’t simply releasing songs around whatever topic happens to be commercially convenient. She appears increasingly interested in using accessible music to examine how people treat one another.

Chicago is an appropriate city for that conversation because community here isn’t an abstraction. It’s embedded in the city’s culture. Neighborhood festivals, corner bars, churches, block clubs, independent venues, and family businesses survive because people continually invest in the places and people around them.

In other words, they put down roots.

There is room for Harve to push the musical side of her concept further. “Have You Loved Like a Tree?” maintains a consistently reflective atmosphere, but greater dynamic contrast could deepen its emotional impact. Chicago’s gospel tradition understands this instinctively: begin intimately, build patiently, and eventually let the music rise until contemplation becomes release.

A more dramatic final passage could give Harve’s message additional force without compromising the song’s tenderness.

Still, its restraint has purpose.

The recording doesn’t shout because the tree doesn’t need to.

That’s ultimately what makes the metaphor stick.

Think about a Chicago tree in February. There are no leaves. No evidence of growth. Nothing outwardly spectacular is happening. Yet beneath the surface, life remains. The roots haven’t abandoned their work simply because nobody can see the results.

There is something beautiful in that image, and something distinctly relevant to Harve’s definition of love.

Real devotion isn’t always dramatic.

Sometimes it’s showing up.

Sometimes it’s surviving winter together.

Sometimes it’s standing quietly beside someone until their spring returns.

That is where “Have You Loved Like a Tree?” moves beyond its unusual title and becomes something genuinely affecting. Harve takes an everyday object and asks listeners to reconsider it as a model for human behavior.

In a culture dominated by speed, visibility and instant reaction, she’s advocating something slower: patience without recognition, strength without performance and generosity without expectation.

Chicago understands all three.

Harve’s memorable central metaphor, sincere vocal delivery, and understated production give the single emotional staying power. Greater dynamic development could make the musical journey even stronger, but the song accomplishes the most important task: it leaves listeners thinking after it ends.

In the Windy City, where every year brings another test of what can survive the season, Shweta Harve’s question lands with particular force.

When the cold comes, will your love still have roots?

Cook County Forest Preserve Teamsters Win Higher Wages and Paid Lunch After 16-Day Strike

Members of Teamsters Local 700 ratified a new contract with the Forest Preserve District of Cook County on September 2, 2026, ending a 16-day strike by approximately 230 truck drivers, laborers, mechanics, and resource technicians. The agreement includes higher wages, paid lunch breaks, overtime pay for sixth and seventh consecutive days worked, and new seniority-based bidding language for shift assignments. The strike was the first in the local’s history.

Key Takeaways

  • Approximately 230 Teamsters Local 700 members walked off the job on August 17, 2026, after rejecting the Forest Preserve District’s “last, best, and final offer” twice, first in late 2025 and again in July 2026.
  • The ratified contract includes a succession of raises, one-time payments for full-time and seasonal employees, paid lunch and breaks, overtime pay for sixth and seventh days worked, and seniority-based bidding procedures for shift assignments and weekend work reduction.
  • The union’s central grievance was a pay scale that advanced non-union forest preserve employees through their salary steps at roughly 10 times the rate of Teamster-represented workers.
  • The wage scale itself was not restructured in the new agreement. The contract expires December 31, 2027, and management has agreed to begin bargaining the next agreement as early as January.
  • Six other unions at the forest preserves had already accepted similar or identical terms to the district’s original offer. Teamsters Local 700 was the only unit to reject it and strike.

The Pay Scale Gap Drove the Dispute

The contract between Teamsters Local 700 and the Forest Preserve District of Cook County expired at the end of December 2025. The district’s initial offer included an 8 percent pay increase spread across two years: 2 percent retroactive to January 2026, another 2 percent starting July 2026, and 4 percent in July 2027. The package also included a $2,500 one-time payment for full-time employees and $1,250 for seasonal staff, a paid half-hour lunch, and expanded overtime rules. Six other unions representing forest preserve workers accepted those terms or similar versions.

Teamsters Local 700 rejected the offer twice. The issue was not the percentage raise itself but the underlying pay scale. Local 700 Vice President Anthony McGee described the disparity in structural terms: Teamsters members’ wages increased by less than three-quarters of a percent on average at each step in their pay progression, while non-union employees at the same agency received approximately 5 percent per step. That gap had compounded over decades, leaving the Teamster-represented workforce earning significantly less than workers in comparable positions at the Cook County Department of Transportation and Highways, the Chicago Park District, the City of Chicago, the Illinois Tollway, and the Illinois Department of Transportation.

Teamsters Local 700 President Ramon Williams framed the imbalance in direct terms before the strike began. The district, Williams said, advanced non-union staff through its pay scale at 10 times the rate of its Teamster-represented employees while simultaneously contracting out work that fell within the bargaining unit’s scope. The combination of stagnant step progression and outsourced labor formed the basis for the union’s decision to reject two offers and walk out.

The 16-Day Strike Was a First for Teamsters Local 700

The strike began on August 17, 2026, after members authorized the action on July 30 by an overwhelming margin. The walkout put approximately 230 workers on the picket line, including certified arborists, truck drivers, laborers, and mechanics responsible for road clearing, trail maintenance, equipment upkeep, trash collection, and prescribed burns across the Cook County forest preserve system. Roughly 40 to 60 of the striking workers were seasonal employees; the remainder were full-time.

The Forest Preserve District kept all trails, picnic groves, campgrounds, nature centers, and golf courses open throughout the strike. General Superintendent Adam Bianchi said the district recognized the value of Local 700’s workforce but was operating within fiscal constraints. The district’s position was that its compensation package remained competitive within the broader labor market. The union’s position was that the district’s own internal comparisons told a different story.

The strike drew support from outside the bargaining unit. Chicago DSA’s Labor Branch organized picket line visits, and Teamsters for a Democratic Union highlighted the dispute as part of a broader pattern of public-sector labor activity in the Chicago region. The walkout ran through rain and late-summer heat across 16 days before ending with a ratification vote on September 2.

What the New Contract Includes and What It Leaves Unresolved

The ratified agreement delivered gains on several of the issues that drove the strike. The contract includes a succession of wage increases, though the union did not disclose specific percentages beyond what the district had originally proposed. One-time payments for full-time and seasonal employees were retained. Paid lunch breaks and rest periods, which non-union staff already received, were formalized for the Teamster-represented workforce. Overtime pay now applies to sixth and seventh consecutive days worked. New bidding language requires the district to honor seniority in shift assignment decisions, and scheduling procedures were revised to reduce mandatory weekend work and improve advance notification.

What the contract did not deliver was a restructuring of the wage scale. The step-rate disparity between union and non-union employees, the issue that Local 700 identified as its central demand before and during the strike, remains in place. Members acknowledged the gap publicly in statements following ratification.

David Yokley, a laborer, described the outcome as a partial victory. The contract secured meaningful improvements on working conditions, but the wage scale still falls short of what non-union forest preserve workers and comparable public-sector employees elsewhere in Cook County earn. The new agreement expires December 31, 2027, and management has agreed to begin bargaining the successor contract as early as January. Local 700 members have described that timeline as the window in which the wage scale fight will resume.

The Strike Fit into a Broader Wave of Chicago Labor Activity

The Forest Preserve Teamsters’ walkout was not an isolated event. The strike’s 16-day duration overlapped with a period of elevated labor activity across the Chicago region. Hotel workers and nurses in the city were also engaged in strike actions reported over the Labor Day holiday weekend. The Chicago Labor Day Parade returned on September 5 to the East Side neighborhood on the Southeast Side for the first time since 2022, drawing union members, retirees, and labor advocates to South Ewing Avenue in a march that included dozens of unions.

The parade’s return to the East Side, a historically industrial and union-dense neighborhood, carried symbolic weight during a week that also saw the Teamsters ratify their forest preserve contract and multiple other labor actions reach public visibility. Members of Local 700 formed a rank-and-file member action committee during the strike that the local has now agreed to formalize as a permanent organizing structure heading into the 2027 contract cycle. Brannon Curtis-Wittenberg, a senior resource technician, said the committee built relationships across all four forest preserve departments and that the local now sees it as a model for how to prepare for the next round of bargaining.

FAQs

How Long Did the Forest Preserve Teamsters Strike Last?

The strike lasted 16 days, from August 17 through September 2, 2026, when Teamsters Local 700 members ratified a new contract with the Forest Preserve District of Cook County. It was the first strike in the local’s history.

What Did the New Contract Include?

The agreement includes higher wages through a succession of raises, one-time payments for full-time and seasonal employees, paid lunch breaks, overtime pay for sixth and seventh consecutive days worked, new seniority-based bidding for shift assignments, and scheduling changes to reduce mandatory weekend work.

Was the Wage Scale Restructured?

No. The underlying pay scale, which advances non-union employees through salary steps at roughly 10 times the rate of Teamster-represented workers, was not changed in this contract. The union has identified wage scale reform as its priority for the next bargaining cycle, which management has agreed to begin as early as January 2027.

Were the Forest Preserves Closed During the Strike?

No. The Forest Preserve District of Cook County kept all trails, picnic groves, nature centers, campgrounds, and golf courses open to the public throughout the 16-day strike.

A Three-Step Process for Exploring Business Financing Options Before Applying

Understanding whether a business genuinely qualifies for financing used to require submitting a full application and waiting for an answer. A structured, three-step process now lets business owners get that same answer, in outline form, before committing to anything at all.

Step One: Understanding Whether You Qualify

Fundivi, a direct lender and hybrid funding platform, built its self-underwriting engine as the natural first step in this process. A business owner enters nine specific numbers, revenue, average daily balance, negative balance days, time in business, credit score, state, industry, open positions, and existing monthly payments, and receives an immediate, honest qualification outlook. This step answers the most fundamental question first. Is this business in a realistic range for approval, and roughly how much might it access?

The tool updates live as each number is entered, with no submit button, no credit pull, and nothing stored anywhere. This means a business owner can explore different scenarios: what happens if leverage comes down, what happens if the average balance improves, without any risk or commitment involved.

Step Two: Understanding Which Product Fits

Once qualification looks realistic, the natural second step becomes the funding product matcher, which addresses a different question altogether. Of the products a business might qualify for, which one actually fits how the business runs and what the money is for? Eleven questions across four short steps, revenue and cash, business profile, existing debt, and funding needs, produce a recommended product with the reasoning explained plainly, plus a second option worth considering.

This second step matters because qualification and fit are separate questions. A business might qualify for several different products but need only one specific structure based on its actual situation, and applying for the wrong one, even when technically eligible, can mean financing that doesn’t solve the underlying problem efficiently.

Step Three: Understanding What It Actually Costs

The third and final step happens once a real offer is in hand: confirming what it costs using the cost calculator. Because business financing is priced using a factor rate rather than a traditional interest rate, this step converts that offer into a true annualized figure that can be fairly compared against other options, revealing a cost that often looks meaningfully different from the factor rate alone.

Why This Sequence Matters

Moving through these three steps in order mirrors how a real financing decision unfolds, starting broad with whether financing is realistic at all, narrowing to which specific product fits, and finishing with whether a resulting offer is fair. Skipping directly to an application without this sequence means making each of these decisions blind, with considerably less information than a few minutes of preparation would have provided.

What Happens When Business Owners Skip Steps

Business owners who skip directly to applying without working through this sequence often encounter one of several avoidable outcomes. Some discover mid-application that they’re not yet in a realistic qualification range, having invested time into a request unlikely to succeed. Others get approved but for a product that doesn’t address their underlying need efficiently, discovering only after the fact that a different structure would have served them better. Still others accept a factor rate offer without understanding its true annualized cost, recognizing only later, sometimes well into repayment, just how much more expensive the financing turned out to be than they first assumed.

Each of these outcomes traces back to skipping one of the three steps this process is designed to address. The sequence isn’t an arbitrary bureaucratic hurdle, it’s a reflection of the actual decisions a business owner needs to make correctly, in order, to end up with financing that fits their situation.

How the Three Steps Build on Each Other

Each step in this process informs the next. A business owner’s qualification outlook from step one shapes which products are realistically available in step two, since the product matcher weighs many of the same underlying factors, credit score, time in business, leverage, that the underwriting engine evaluates. The specific product identified in step two then shapes what a business owner should expect to see once real offers arrive, since working capital, bridge capital, term loans, and lines of credit each carry different typical pricing structures that step three’s cost calculator is built to evaluate accurately.

This interconnection means working through the steps in order matters, rather than treating them as three unrelated tools a business owner might use in any sequence. Understanding qualification first provides essential context for understanding product fit, which in turn provides context for evaluating whether a specific offer’s cost is reasonable given the product type and the business’s underlying risk profile.

Why This Process Reflects a Broader Shift in Business Lending

This three-step structure reflects a broader shift already underway across business lending, moving away from a single, opaque application process toward a more transparent, staged approach that gives business owners visibility at each decision point along the way. As more lenders adopt similar technology-driven tools, business owners are likely to expect this kind of staged clarity as a baseline standard, rather than treating it as a notable exception within an otherwise opaque industry.

Applying This Process Even When Working With a Different Lender

The logic behind this three-step sequence remains useful even for business owners ultimately considering a lender other than Fundivi. Understanding your own qualification profile, clarifying which product structure fits your needs, and knowing how to convert any factor rate offer into a true annualized cost are all skills that transfer directly to evaluating financing from any source, not just the specific tools Fundivi happens to provide.

This is part of why the transparency behind these tools carries value beyond a single platform. A business owner who internalizes this way of thinking, qualification, fit, then cost, approaches every future financing decision with more sophistication than someone encountering these questions for the first time only after a lender has already presented them with a specific offer to evaluate under time pressure.

How to Revisit This Process as Your Business Changes

Because a business’s revenue, credit profile, and existing debt load can all shift over time, this three-step process isn’t something to complete only once. A business owner who checked their qualification outlook a year ago, when the business looked considerably different, benefits from revisiting that check periodically, particularly before a new financing decision, rather than assuming last year’s outlook still reflects where the business stands today.

Frequently Asked Questions

Do I Have To Complete All Three Steps Before Applying?

No, but each step provides genuinely useful information. Business owners can use just one, all three, or return to any of them repeatedly without any commitment required.

How Long Does The Full Three-Step Process Actually Take?

Most business owners can complete all three steps in under twenty minutes combined, considerably faster than the days or weeks a traditional application process typically requires for even an initial answer.

Is Step Three Only Useful If I Have An Offer From Fundivi?

No. The cost calculator works for any factor rate offer, regardless of which lender issued it.

What If Step One Shows I Don’t Currently Qualify?

The factor-by-factor breakdown shows specifically which number is holding your outlook back, giving you a concrete target to address before revisiting the process later.

Can I Skip Step Two If I Already Know Which Product I Want?

Yes, though many business owners discover through step two that a different product than the one they initially assumed actually fits their situation better.

Getting Started

Business owners ready to move through this process can begin with the underwriting engine, confirm product fit next, and finish by checking any resulting offer’s true cost before making a final decision.

Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or lending advice. Results generated by the tools described are estimates and do not represent guaranteed approval, eligibility, rates, terms, or funding amounts. Actual offers and costs depend on lender underwriting, verification, and the applicant’s financial circumstances. Business owners should review all financing terms carefully and consult a qualified professional when appropriate.